Services

Company RegistrationVisa ServicesBanking ServicesAccounting ServicesLegal ServicesHR Services

Partners

Partner modelsReferral program

Resources

BlogNews

About the company

About UsContact us

Latest articles


UPPERSETUP logo

Online platform for business registration in the UAE

Email

support@uppersetup.com

Phone

+971 52 184 1181

© 2026 UPPERSETUP Technology Ltd.
All content on this website is protected by copyright

Terms of ServiceTerms of UsePrivacy Policy
Send WhatsApp message
  1. Home
  2. Blog
  3. Legal services

Legal services

All articles
RERA
Bankruptcy
Fujairah Free Zone
JAFZA
IT-startups
Hong Kong
RAKICC
Accounting
ADAFZ - Abu Dhabi Airport Free Zone
Personal Data
Laws and Regulations
Dubai International Academic City
Company Re-domiciliation
Dubai Maritime City
Meydan Free Zone
Fund
DWTC
Dubai South Free Zone
DIAC
Visas
Government programs
Healthcare
RAKEZ
Masdar City Free Zone
CRS
UAQ Free Trade Zone
Legal services
UAE
Digital Assets
Комплайнс
Knowledge base
UPPERSETUP
Work permit
Permits and Approvals
DIFC
Property
Finance
Deadlines & Рrocess
Offices & Infrastructure
Commercial Arbitration
Dubai Media City
Company setup
Dubai Knowledge Park
SAIF Zone
Investments
Banking
Dubai Silicon Oasis
KEZAD
Dubai Production City
Intellectual Property
HR
Dubai Design District (d3)
Innovation City
Free Zone
Dubai Industrial City
Dubai Studio City
Dubai Science Park
Virtual assets
arbitrateAD
Astana Hub
Dubai Healthcare City
Business
Hamriyah Free Zone
Customs
AML
Sharjah Media City
Trademark Registration
AIFC
Kazakhstan
DMCC
Tax
DAFZA
Hong Kong
Education Industry
Dubai CommerCity
Dubai Outsource City
Trade
twofour54
Industries
ADGM
Certification
Regulatory environment
Dubai Internet City
Residence Permit
Cybersecurity
Ajman Free Zone
Service

Recommended

DNFBP AML Compliance in the UAE 2026: Who Is Covered, What’s Required, and Who Supervises
Legal servicesAMLUAE

DNFBP AML Compliance in the UAE 2026: Who Is Covered, What’s Required, and Who Supervises

DNFBP (Designated Non-Financial Businesses and Professions) is a category of businesses that are not financial institutions but must comply with AML/CFT requirements on par with banks: real estate agents, dealers in precious metals and stones, trust and company service providers, accountants, auditors, lawyers, notaries, and commercial gaming operators.

UAE DMTT 2026: The 15% Top-Up Tax for Large Multinational Enterprises
Legal servicesTaxKnowledge baseUAE

UAE DMTT 2026: The 15% Top-Up Tax for Large Multinational Enterprises

The Domestic Minimum Top-up Tax (DMTT) is a UAE tax topping up the effective tax rate to 15%, introduced by Cabinet Decision No. 142 of 2024 and applicable for financial years beginning on or after 1 January 2025. It applies only to multinational groups with consolidated annual revenue of €750 million or more in at least two of the preceding four financial years. This implements the OECD/G20 Pillar Two global standard (GloBE Model Rules). For the vast majority of small and medium-sized businesses, this tax does not apply — the €750m threshold filters out everything except the largest-scale groups.

UAE Family Foundation 2026: Tax Transparency Under Article 17 of the Corporate Tax Law
Legal servicesTaxADGMUAEDIFCRAKICC

UAE Family Foundation 2026: Tax Transparency Under Article 17 of the Corporate Tax Law

A Family Foundation in the UAE is not a distinct legal entity type — it is a tax status. Article 17 of Federal Decree-Law No. 47 of 2022 (the Corporate Tax Law) allows a foundation, trust, or similar entity to obtain Unincorporated Partnership status — fiscal transparency under which income is taxed in the hands of the beneficiaries rather than at the level of the structure itself. Trusts without separate legal personality (such as DIFC/ADGM trusts) are automatically transparent. Foundations with separate legal personality (DIFC Foundation, ADGM Foundation, RAK ICC Foundation) must apply to the Federal Tax Authority (FTA) and obtain approval. For individual beneficiaries, personal investment and real estate income is generally outside Corporate Tax regardless of the foundation’s own transparency status.

The UAE Finfluencer License 2026: Registering Financial Content Creators with the SCA
Legal servicesKnowledge baseUAE

The UAE Finfluencer License 2026: Registering Financial Content Creators with the SCA

The Finfluencer License is mandatory registration with the Securities and Commodities Authority (SCA) for any individual providing financial recommendations via social media who has 1,000 or more followers.

UAE R&D Tax Credit 2026: Up to 50% Credit on Qualifying R&D Expenditure
Legal servicesTaxKnowledge baseUAE

UAE R&D Tax Credit 2026: Up to 50% Credit on Qualifying R&D Expenditure

The R&D Tax Credit is a non-refundable UAE tax credit on qualifying research and development expenditure, introduced by Cabinet Decision No. 215 of 2025 and Ministerial Decision No. 24 of 2026, applicable for tax periods beginning on or after 1 January 2026. The credit rate is tiered: 15%, 35%, and 50%, depending on both the level of R&D expenditure and the average number of staff dedicated to R&D. The maximum credit is AED 2 million per tax period (50% of the maximum qualifying expenditure of AED 5 million). The credit is applied against Corporate Tax liability and, where applicable, Top-up Tax (DMTT).

UAE Small Business Relief 2026: Last Chance for 0% Corporate Tax Before 31 December
Legal servicesTaxUAE

UAE Small Business Relief 2026: Last Chance for 0% Corporate Tax Before 31 December

Small Business Relief (SBR) is a transitional measure under the UAE corporate tax framework. Any UAE-resident taxable person with revenue at or below AED 3 million may elect SBR and be treated as having zero taxable income for that tax period — effectively 0% corporate tax. SBR is available only for tax periods ending on or before 31 December 2026. The UAE Ministry of Finance has not announced any extension.

UAE Bankruptcy and Insolvency Law 2026: Procedures, Director Liability, and Business Protection
Legal servicesUAE

UAE Bankruptcy and Insolvency Law 2026: Procedures, Director Liability, and Business Protection

Corporate bankruptcy and restructuring in the UAE is governed by Federal Decree-Law No. 51 of 2023 (Financial Restructuring and Bankruptcy Law), in force since 1 May 2024. A debtor must file an application within 60 days from the date payments are suspended or from the date it becomes aware it will be unable to meet its debts. There are three procedures: preventive settlement (before formal bankruptcy), restructuring, and liquidation. Since 15 July 2025, all cases are heard by a dedicated Bankruptcy Court based in Abu Dhabi. DIFC and ADGM companies are excluded and follow their own separate insolvency regimes.

UAE VAT Refund for Businesses in 2026: Procedure, Deadlines, and the New 5-Year Rule
Legal servicesTaxUAE

UAE VAT Refund for Businesses in 2026: Procedure, Deadlines, and the New 5-Year Rule

A UAE VAT-registered business can claim a refund of excess input tax through the FTA EmaraTax portal using Form VAT311, after submitting the relevant VAT201 return. The FTA reviews the application within 20 working days; approved refunds are paid within 5 working days. The critical 2026 change: under Federal Decree-Law No. 16 of 2025, excess input VAT can no longer be carried forward indefinitely. The maximum carry-forward period is now 5 years. Transitional deadline: credits from 2018–2020 must be claimed by 31 December 2026 or they lapse permanently.

DIFC, ADGM, and ADJD Wills: Inheritance Planning in the UAE for Non-Residents
Legal servicesDIFCADGMUAE

DIFC, ADGM, and ADJD Wills: Inheritance Planning in the UAE for Non-Residents

Without a registered will, the UAE-based assets of a non-Muslim non-resident (bank accounts, real estate, shares in a company) are distributed under Article 11 of Federal Decree-Law No. 41 of 2022 on Civil Personal Status: 50% to the spouse, 50% split equally among the children. Bank accounts are frozen immediately on notification of death until a court establishes the heirs — a process that can take anywhere from a few months to over a year. Three main registrars allow proactive registration: DIFC Wills Service (AED 10,000, English only), ADJD in Abu Dhabi (AED 950, bilingual), and ADGM (registration at ADGM, probate handled through ADJD). UAE residency is not required for any of the three.
UAE Personal Data Protection Law (PDPL): The Complete Business Guide for 2026
Legal servicesUAE

UAE Personal Data Protection Law (PDPL): The Complete Business Guide for 2026

On 20 September 2021, the UAE enacted its first comprehensive federal data privacy framework: Federal Decree-Law No. 45 of 2021 on the Protection of Personal Data — universally referred to as the PDPL. The law came into force on 2 January 2022.

UAE Commercial Agency Law 2026: Agent Protection, Registration, and the Risks for a Foreign Principal
Legal servicesUAE

UAE Commercial Agency Law 2026: Agent Protection, Registration, and the Risks for a Foreign Principal

A commercial agency in the UAE is an agreement registered with the Ministry of Economy that grants a local agent statutory protections — including a restriction on unilateral termination and a right to compensation — that an ordinary, unregistered distributor does not have.

The UAE Family Business Law 2026: Federal Decree-Law No. 37 of 2022 — the Registry, Share Succession, and Dispute Resolution
Legal servicesUAE

The UAE Family Business Law 2026: Federal Decree-Law No. 37 of 2022 — the Registry, Share Succession, and Dispute Resolution

Federal Decree-Law No. (37) of 2022 Concerning Family Businesses is the UAE’s first federal law regulating operating companies owned by a single family through voluntary registration in a family business registry, rather than through creating a separate asset-holding structure.

Cybersecurity Law in the UAE 2026: The Cybercrimes Statute, Regulators, and Critical Infrastructure Protection
Legal services

Cybersecurity Law in the UAE 2026: The Cybercrimes Statute, Regulators, and Critical Infrastructure Protection

Cybersecurity in the UAE is governed by a multi-layered system: a base criminal cybercrimes statute applies federally, with sector-specific and emirate-level regulatory requirements layered on top depending on the company’s industry and licence.

Commercial Arbitration in the UAE 2026: DIAC, arbitrateAD, and What Happened to Old DIFC-LCIA Clauses
Legal servicesCommercial ArbitrationDIACarbitrateADUAE

Commercial Arbitration in the UAE 2026: DIAC, arbitrateAD, and What Happened to Old DIFC-LCIA Clauses

Commercial arbitration in the UAE is governed by the federal Federal Law No. 6 of 2018 on Arbitration, but the actual landscape of arbitration institutions has changed substantially over the past five years.

UAE Corporate Tax 2026: Rates, QFZP, Small Business Relief, Deadlines and Penalties — The Complete Guide
Legal servicesTaxKnowledge baseUAE

UAE Corporate Tax 2026: Rates, QFZP, Small Business Relief, Deadlines and Penalties — The Complete Guide

Corporate tax (CT) is a federal tax on profits of legal entities and natural persons from business activities in the UAE, introduced by Federal Decree-Law No. 47 of 2022. In force from 1 June 2023. For the first time in UAE history, a direct profits tax applies to the vast majority of commercial entities.

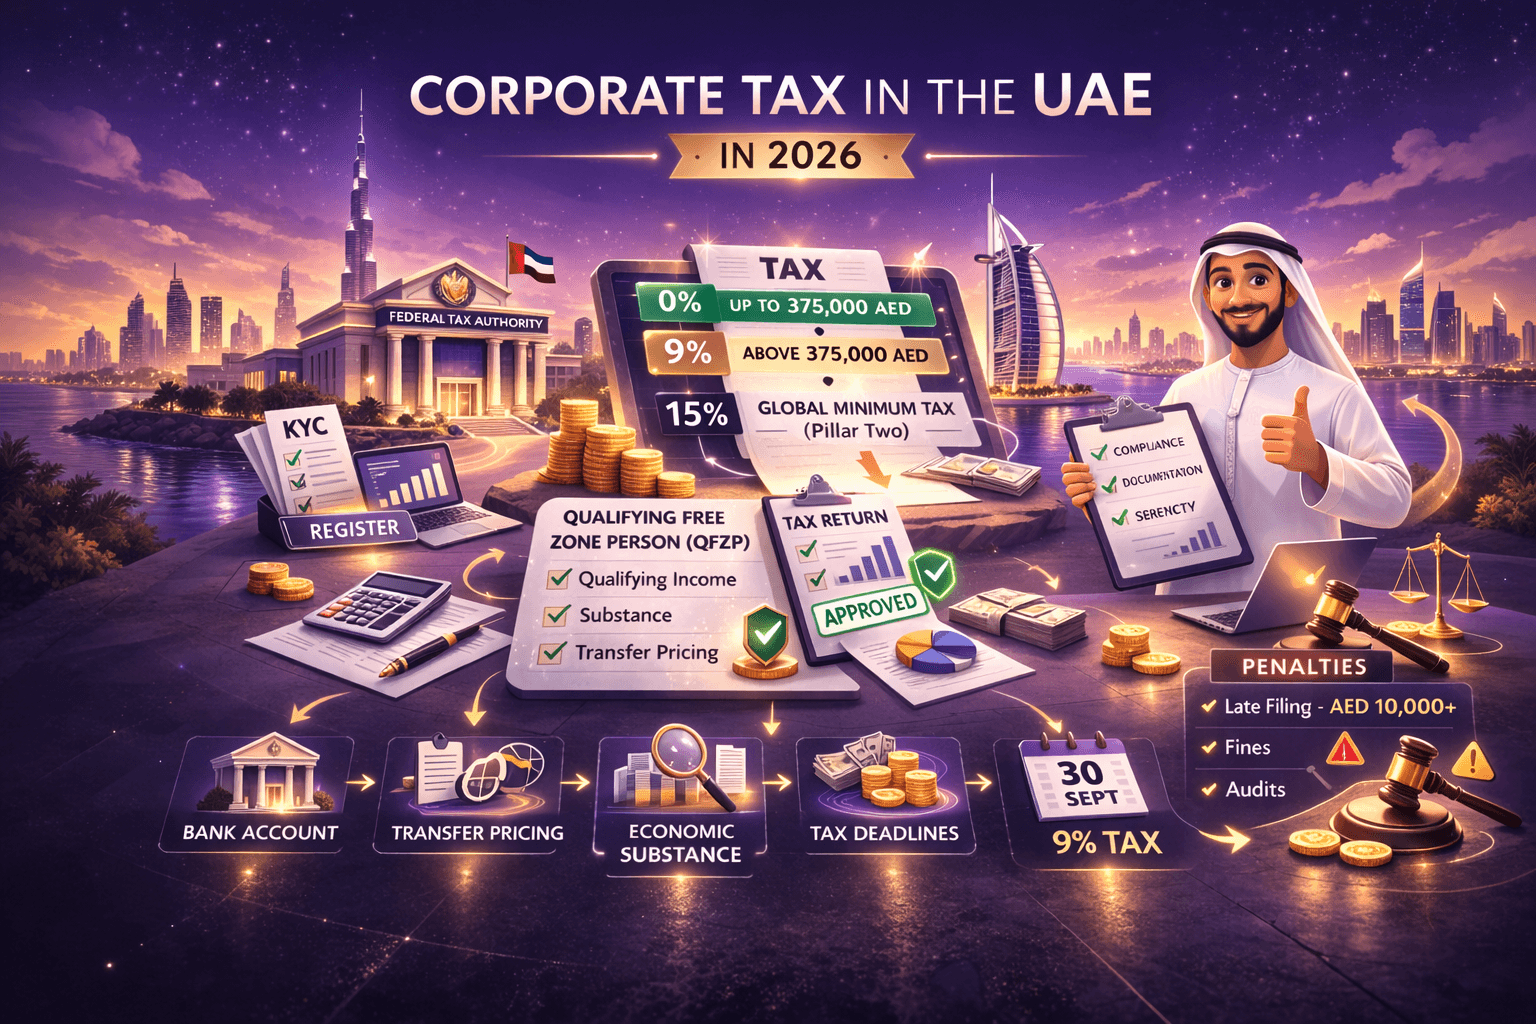
Corporate Tax in the UAE in 2026: A Detailed Analysis for Business Owners and Advisors
Legal servicesKnowledge base

Corporate Tax in the UAE in 2026: A Detailed Analysis for Business Owners and Advisors

Since 1 June 2023, the United Arab Emirates has operated under Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses. By 2026, this regime has become fully embedded in banking, investment, and compliance practice.
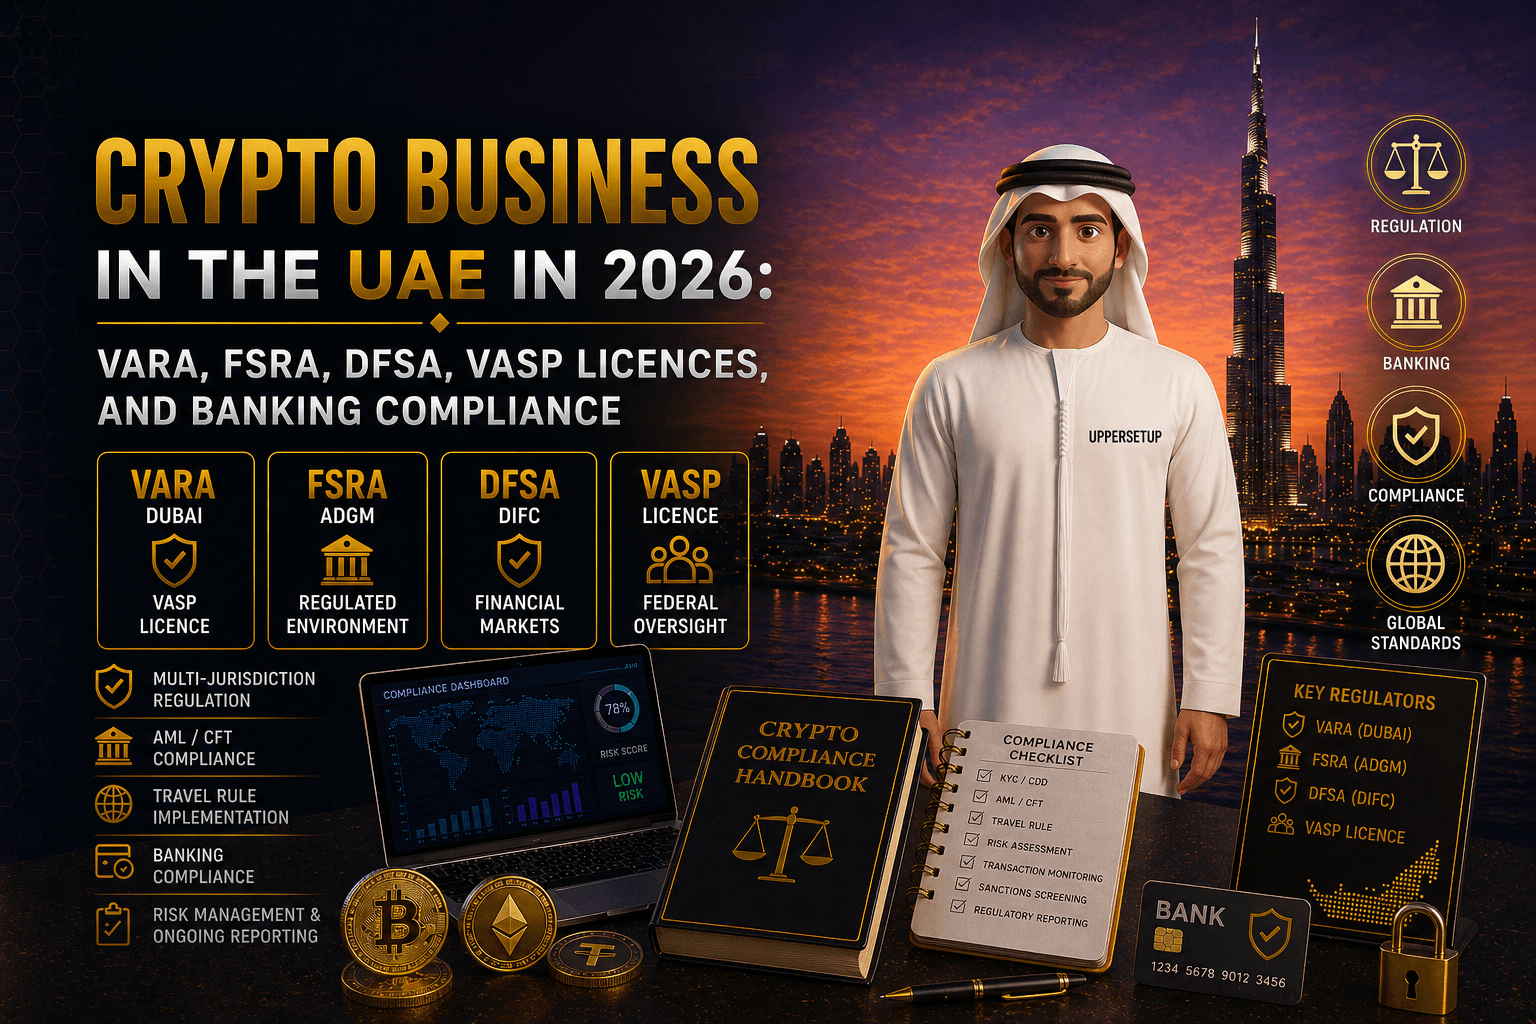
Crypto Business in the UAE in 2026: VARA, FSRA, DFSA, VASP Licences, and Banking Compliance
Legal servicesKnowledge baseUAE

Crypto Business in the UAE in 2026: VARA, FSRA, DFSA, VASP Licences, and Banking Compliance

The UAE occupies a unique position in the global virtual asset regulatory landscape. It is the only country in the world to have established a dedicated regulatory authority exclusively for virtual assets — VARA in Dubai — as early as 2022, long before most jurisdictions had begun drafting any coherent rules.

Liquidating and Closing a UAE Company in 2026: Licence Cancellation, Corporate Tax and VAT Deregistration, Final Returns, Visas and Director Liability
Legal servicesDeadlines & РrocessLaws and RegulationsUAE

Liquidating and Closing a UAE Company in 2026: Licence Cancellation, Corporate Tax and VAT Deregistration, Final Returns, Visas and Director Liability

Closing a UAE company is not one procedure but three running in parallel: the corporate track (liquidation and licence cancellation), the tax track (deregistration with the Federal Tax Authority for corporate tax and VAT) and the immigration track (cancelling visas and the establishment card). The framework is set by Federal Decree-Law No. 32 of 2021 on Commercial Companies as amended by Federal Decree-Law No. 20 of 2025, Federal Decree-Law No. 47 of 2022 on Corporate Tax, Federal Decree-Law No. 8 of 2017 on VAT and Federal Decree-Law No. 28 of 2022 on Tax Procedures.

Liquidating an LLP in Kazakhstan in 2026: the Rules in Force, the Deadlines and the "Clean Slate" Mechanism
Legal servicesKazakhstanLaws and Regulations

Liquidating an LLP in Kazakhstan in 2026: the Rules in Force, the Deadlines and the "Clean Slate" Mechanism

Liquidating a limited liability partnership in Kazakhstan runs on two parallel tracks: a corporate one, handled by the justice authorities and ending with the removal of the entry from the National Register of Business Identification Numbers, and a tax one, handled by the state revenue authorities and determining how long the whole exercise actually takes. The second track was rewritten in full with effect from 1 January 2026.

UAE Personal Tax Residency 2026: The Complete Guide — Three Tests, the TRC, and the DTT Network
Legal servicesTaxVisasUAE

UAE Personal Tax Residency 2026: The Complete Guide — Three Tests, the TRC, and the DTT Network

A UAE residence visa is an immigration status. It authorises living and working in the UAE. It is issued by ICP or GDRFA.

UAE tax residency is a tax status. It confirms that an individual is a tax resident of the UAE. It is evidenced by a Tax Residency Certificate (TRC) issued by the Federal Tax Authority (FTA).

UAE Tax Residency During Extended Absence: How Not to Lose Your TRC
Legal servicesTaxUAE

UAE Tax Residency During Extended Absence: How Not to Lose Your TRC

UAE tax residency and immigration status are two separate things. A residence visa (including the Golden Visa) protects immigration status but does not make you a UAE tax resident. Tax residency is determined by physical presence and other factors under Cabinet Decision No. 85 of 2022. During extended absence, two independent risks arise: loss of UAE tax residency and potential tax residency in the country of stay.

UAE Changed Its Company Law: What Is Now Permitted, What Has Changed, and What to Review Urgently
Legal servicesCompany setupKnowledge baseUAE

UAE Changed Its Company Law: What Is Now Permitted, What Has Changed, and What to Review Urgently

Federal Decree-Law No. 20 of 2025 took effect on 15 October 2025. It amended Federal Decree-Law No. 32 of 2021 on Commercial Companies — the UAE's primary corporate law. The main changes: companies can now transfer between jurisdictions without liquidation (re-domiciliation), LLCs can issue multiple share classes, drag-along and tag-along rights are now statutory, and free zone companies conducting mainland activities are expressly subject to the CCL.

Non-Compete Clauses in UAE Employment Contracts 2026: When They’re Valid and How to Challenge Them
Legal services

Non-Compete Clauses in UAE Employment Contracts 2026: When They’re Valid and How to Challenge Them

A non-compete clause in a UAE employment contract is valid only when three conditions are met simultaneously: the employee had access to the employer’s clients or business secrets, the restriction is precisely defined by time, place, and type of activity, and the duration does not exceed two years from the contract’s expiry.

The Offshore Profits Claim in Hong Kong: How the Territorial Source Principle Works in 2026
Legal servicesCompany setupHong Kong

The Offshore Profits Claim in Hong Kong: How the Territorial Source Principle Works in 2026

Hong Kong charges profits tax only on profits arising in or derived from Hong Kong. The residence of the taxpayer is irrelevant. A Hong Kong company may therefore lawfully pay no profits tax where the operations that produced the profits were carried out outside Hong Kong. That position is asserted through an offshore claim, which is neither a relief nor a permissive procedure: it is the application of section 14 of the Inland Revenue Ordinance (Cap. 112).

Relocating a Business to the UAE from Another Jurisdiction: Structures, Tax Consequences, and What Formation Agencies Don't Tell You
Legal servicesUAE

Relocating a Business to the UAE from Another Jurisdiction: Structures, Tax Consequences, and What Formation Agencies Don't Tell You

Relocating a founder to the UAE and moving a business to the UAE are not the same thing. The first is resolved through obtaining a residence visa and, upon satisfying the criteria of Cabinet Resolution No. 85 of 2022, UAE tax residency. The second is a multi-layered corporate and tax task in which every decision carries consequences in several jurisdictions simultaneously.

Buying Real Estate in Kazakhstan as a Foreigner 2026: Housing, Land, and the Risks of Structuring Through a Legal Entity
Legal servicesKazakhstanProperty

Buying Real Estate in Kazakhstan as a Foreigner 2026: Housing, Land, and the Risks of Structuring Through a Legal Entity

A foreigner may acquire residential property in Kazakhstan only with permanently residing status (a residence permit holder); without that status, the right to housing under Article 9 of the Law of the RK “On the Legal Status of Foreigners” does not extend to a foreign national.

Trademark Registration in the UAE 2026: A Complete Guide to the Process, Timeline, and Costs
Legal servicesUAE

Trademark Registration in the UAE 2026: A Complete Guide to the Process, Timeline, and Costs

Trademark registration in the UAE is governed by Federal Decree-Law No. (36) of 2021 on Trademarks and administered by a single federal authority — the Ministry of Economy and Tourism (MOET) through its Trademark Office. Registration is effective across all 7 emirates at once, costs from AED 6,500 for a single class (application, publication, and registration combined), and takes 4–6 months from filing to certificate under standard conditions. A trademark is valid for 10 years from the filing date and can be renewed indefinitely. As of November 2025, an updated fee schedule applies under Cabinet Resolution No. (102) of 2025, and from 27 January 2026, all new applications are classified under the 13th edition of the Nice Classification.

Redomiciliation Within the UAE: Moving a Company Between Free Zones in 2026. Case Study: IFZA - DAFZA
Legal servicesCompany setupUAE

Redomiciliation Within the UAE: Moving a Company Between Free Zones in 2026. Case Study: IFZA - DAFZA

Before 15 October 2025, changing a UAE free zone meant one thing: liquidate the old company, register a new one. Corporate history was erased, contracts had to be renegotiated, bank accounts closed and reopened, all visas reissued. For a company with three to five years of history, established banking relationships, and an active contract portfolio, this was a significant operational and financial undertaking.

Redomiciliation to the UAE in 2026: The Complete Guide — ADGM, DIFC, and the New Mechanism Under Federal Decree-Law No. 20 of 2025
Legal servicesADGMUAECompany setupDIFC

Redomiciliation to the UAE in 2026: The Complete Guide — ADGM, DIFC, and the New Mechanism Under Federal Decree-Law No. 20 of 2025

Redomiciliation (also known as continuance or delocalisation) is the legal process by which a company transfers its jurisdiction of incorporation from one country to another while preserving its legal personality, corporate history, existing contracts, and all rights and obligations. The company does not cease to exist and is not re-incorporated: it continues to operate as the same legal entity — simply in a new jurisdiction.

Territorial Taxation and Offshore Status in Hong Kong 2026: A Complete Breakdown of How It Actually Works
Legal servicesCompany setupHong KongTax

Territorial Taxation and Offshore Status in Hong Kong 2026: A Complete Breakdown of How It Actually Works

Hong Kong charges Profits Tax only on profits arising in or derived from Hong Kong; profits from foreign sources are not taxed, but only if the company can document that the activity generating the profit genuinely took place outside Hong Kong.

Trusts and private trust companies in Hong Kong in 2026: Cap. 29, the TCSP licence and the tax position
Legal servicesHong KongCompany setup

Trusts and private trust companies in Hong Kong in 2026: Cap. 29, the TCSP licence and the tax position

A Hong Kong trust is governed by the common law and by the Trustee Ordinance (Cap. 29), not by a dedicated trusts statute; the trust itself is not a legal person, and the taxpayer is the trustee. Hong Kong trust law took its present substance on 1 December 2013, when the Trust Law (Amendment) Ordinance 2013 came into force, and has not changed in substance since; the consolidated version of Cap. 29 is nevertheless dated 23 May 2025, because of consequential amendments made by the company re-domiciliation regime.

The UAE Labour Ban 2026: Grounds, Appeals, and How It Differs From a Travel Ban
Legal servicesVisasUAE

The UAE Labour Ban 2026: Grounds, Appeals, and How It Differs From a Travel Ban

A labour ban is an administrative decision by MOHRE blocking the issuance of a new UAE work permit for one year, applied only on three legally defined grounds.

UAE Tax Penalties, Voluntary Disclosure and Appeals in 2026: Tax Assessment Review, Reconsideration, the TDRC and the Courts
Legal servicesTaxUAE

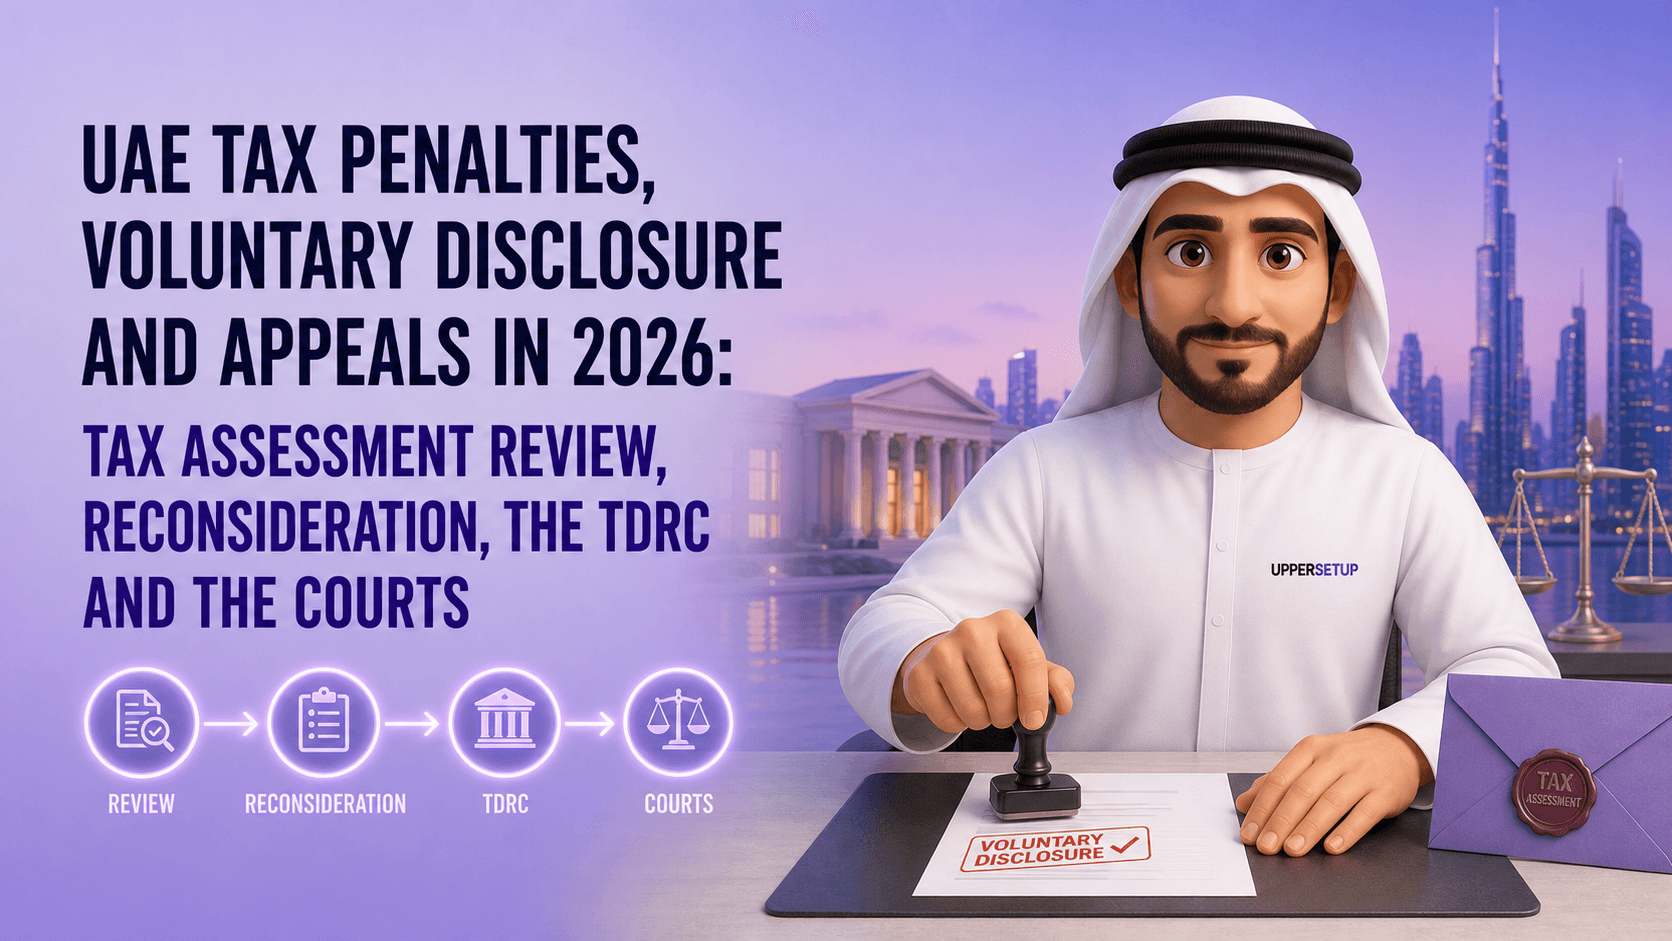
UAE Tax Penalties, Voluntary Disclosure and Appeals in 2026: Tax Assessment Review, Reconsideration, the TDRC and the Courts

A dispute with the UAE Federal Tax Authority runs through four consecutive stages set by Federal Decree-Law No. 28 of 2022 on Tax Procedures: an application for Tax Assessment Review under Article 28, an application for Reconsideration under Article 29, an objection to the Tax Disputes Resolution Committee under Articles 30 to 33, and an appeal to the competent court under Article 36. Skipping a stage closes the next one: a court will not admit a tax claim where no objection was first filed with the Committee.

All articles

DNFBP AML Compliance in the UAE 2026: Who Is Covered, What’s Required, and Who Supervises
Legal servicesAMLUAE

DNFBP AML Compliance in the UAE 2026: Who Is Covered, What’s Required, and Who Supervises

UAE DMTT 2026: The 15% Top-Up Tax for Large Multinational Enterprises
Legal servicesTaxKnowledge baseUAE

UAE DMTT 2026: The 15% Top-Up Tax for Large Multinational Enterprises

UAE Family Foundation 2026: Tax Transparency Under Article 17 of the Corporate Tax Law
Legal servicesTaxADGMUAEDIFCRAKICC

UAE Family Foundation 2026: Tax Transparency Under Article 17 of the Corporate Tax Law

Family Office in the UAE in 2026: DIFC vs ADGM, Foundations, Holding Structures and the New Architecture of Private Wealth
Legal servicesKnowledge base

Family Office in the UAE in 2026: DIFC vs ADGM, Foundations, Holding Structures and the New Architecture of Private Wealth

The UAE Finfluencer License 2026: Registering Financial Content Creators with the SCA
Legal servicesKnowledge baseUAE

The UAE Finfluencer License 2026: Registering Financial Content Creators with the SCA

Place of Effective Management (POEM) in the UAE: When a Foreign Company Becomes a UAE Tax Resident
Legal servicesKnowledge base

Place of Effective Management (POEM) in the UAE: When a Foreign Company Becomes a UAE Tax Resident

UAE R&D Tax Credit 2026: Up to 50% Credit on Qualifying R&D Expenditure
Legal servicesTaxKnowledge baseUAE

UAE R&D Tax Credit 2026: Up to 50% Credit on Qualifying R&D Expenditure

UAE Small Business Relief 2026: Last Chance for 0% Corporate Tax Before 31 December
Legal servicesTaxUAE

UAE Small Business Relief 2026: Last Chance for 0% Corporate Tax Before 31 December

UBO in the UAE in 2026: Real Control, Beneficial Ownership Disclosure, and Tax Risks of Hidden Ownership
Legal servicesKnowledge base

UBO in the UAE in 2026: Real Control, Beneficial Ownership Disclosure, and Tax Risks of Hidden Ownership

UAE Bankruptcy and Insolvency Law 2026: Procedures, Director Liability, and Business Protection
Legal servicesUAE

UAE Bankruptcy and Insolvency Law 2026: Procedures, Director Liability, and Business Protection

UAE VAT Refund for Businesses in 2026: Procedure, Deadlines, and the New 5-Year Rule
Legal servicesTaxUAE

UAE VAT Refund for Businesses in 2026: Procedure, Deadlines, and the New 5-Year Rule

DIFC, ADGM, and ADJD Wills: Inheritance Planning in the UAE for Non-Residents
Legal servicesDIFCADGMUAE

DIFC, ADGM, and ADJD Wills: Inheritance Planning in the UAE for Non-Residents

UAE Personal Data Protection Law (PDPL): The Complete Business Guide for 2026
Legal servicesUAE

UAE Personal Data Protection Law (PDPL): The Complete Business Guide for 2026

UAE Commercial Agency Law 2026: Agent Protection, Registration, and the Risks for a Foreign Principal
Legal servicesUAE

UAE Commercial Agency Law 2026: Agent Protection, Registration, and the Risks for a Foreign Principal

The UAE Family Business Law 2026: Federal Decree-Law No. 37 of 2022 — the Registry, Share Succession, and Dispute Resolution
Legal servicesUAE

The UAE Family Business Law 2026: Federal Decree-Law No. 37 of 2022 — the Registry, Share Succession, and Dispute Resolution